credit:beta.team
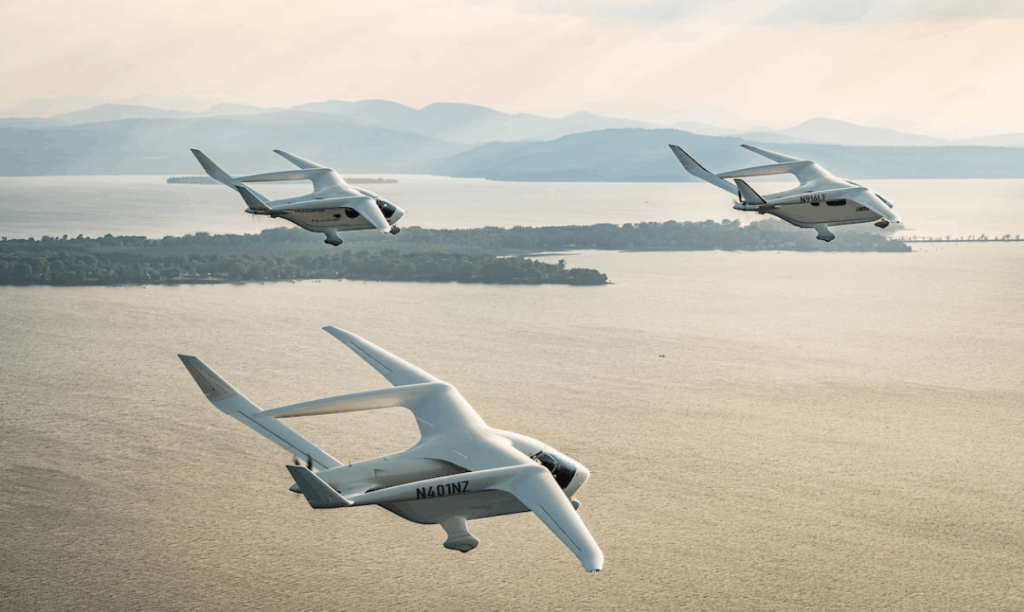
BETA Technologies (NYSE: BETA) may currently look like a broken IPO on the chart, but beneath the weak stock performance sits one of the most operationally advanced companies in the entire electric aviation sector. While many competitors are still focused on concepts, simulations, and future promises, BETA is already flying aircraft, building charging infrastructure, conducting real-world missions, and positioning itself inside the future electric aviation ecosystem.
The market, however, remains skeptical. Despite strong technological progress, major partnerships, growing ETF ownership, and increasing institutional attention, the stock trades far below the enthusiasm levels investors once expected from the eVTOL revolution. The central question is becoming increasingly important:
Is BETA Technologies deeply undervalued relative to its long-term potential — or is the market correctly pricing in the enormous risks still facing the industry?
BETA Technologies Is Not Just Another eVTOL Startup
Founded in Vermont, BETA Technologies focuses on electric aviation systems, particularly electric vertical takeoff and landing (eVTOL) aircraft and electric aerospace infrastructure. The company’s flagship aircraft platform is the ALIA, designed for cargo transport, medical logistics, military applications, and eventually passenger mobility.
Unlike several competitors that primarily market futuristic “air taxi” visions, BETA has intentionally focused on practical deployment first. The company is developing:
- electric aircraft,
- aviation charging networks,
- pilot training ecosystems,
- and integrated aerospace infrastructure.
This broader ecosystem strategy is important because it creates potential recurring revenue streams beyond aircraft sales alone.
According to company materials and industry analysis, BETA’s business model is roughly divided into:
|
Revenue Segment |
Estimated Share |
|
Aircraft Sales & Leasing |
55% |
|
Charging Infrastructure & Services |
25% |
|
Maintenance & Software |
20% |
That structure makes BETA fundamentally different from pure speculative aircraft startups. The charging infrastructure component, in particular, could become strategically valuable if electric aviation adoption accelerates globally.
Why Investors Still Care About BETA Despite Weak Financials
From a traditional valuation perspective, BETA looks expensive and financially weak.
The company currently generates only around $35.6 million in annual revenue, while posting losses approaching $746 million annually. Revenue per employee remains low, and net losses per employee are extremely high, highlighting how aggressively the company is investing into development and infrastructure.
At first glance, these numbers appear alarming.
But early-stage aerospace companies are rarely valued on current earnings.
Instead, investors are pricing:
- future FAA certification,
- future aircraft demand,
- infrastructure dominance,
- military partnerships,
- and long-term market leadership potential.
This is why BETA trades more like a venture-capital-backed technology platform than a traditional industrial manufacturer.
And importantly, unlike many eVTOL peers, BETA has demonstrated real operational progress.
The Biggest Difference Between BETA and Its Competitors
The electric aviation market has become crowded. Major competitors include:
- Joby Aviation
- Archer Aviation
- Lilium
- Vertical Aerospace
- EHang
However, the strategies differ dramatically.
Joby Aviation
Joby is widely viewed as the industry leader in passenger eVTOL development. The company has strong institutional backing and major partnerships, including with Toyota. Its focus remains heavily centered on commercial passenger air taxi networks.
Archer Aviation
Archer aggressively markets urban air mobility and has secured partnerships with airlines and defense-related initiatives. It is more commercially aggressive than BETA but also highly dependent on future certification success.
Lilium
Lilium pursued an ambitious jet-powered eVTOL concept but has struggled with execution challenges and investor confidence issues.
EHang
EHang focuses heavily on autonomous aerial systems in China and has benefited from domestic regulatory support.
Why BETA Stands Out
BETA’s differentiation is operational realism.
Instead of focusing primarily on future passenger taxi dreams, BETA prioritized:
- cargo,
- logistics,
- medical transport,
- military applications,
- and charging infrastructure.
This matters because these markets may commercialize earlier than mass passenger urban mobility.
In many ways, BETA resembles a blend between:
- aerospace manufacturer,
- infrastructure provider,
- and clean transportation platform.
That broader positioning could eventually become a major competitive advantage.
The Infrastructure Strategy Could Be the Hidden Goldmine
One of the market’s most overlooked aspects of BETA is its charging network strategy.
The company is building electric charging infrastructure not just for its own aircraft, but potentially for broader electric aviation ecosystems.
This mirrors what Tesla achieved years ago with Superchargers:
first infrastructure,
then ecosystem dominance.
If electric aviation scales over the next decade, charging networks could become incredibly valuable strategic assets.
The market currently focuses mostly on aircraft certification timelines, but long-term infrastructure ownership may ultimately matter just as much.
This is one reason why several ETFs continue accumulating exposure despite the company’s weak profitability today.
ETF Ownership Suggests Institutions Still Believe in the Sector
BETA already appears in numerous aerospace, drone, clean energy, and innovation ETFs.
Notable exposure includes:
- aerospace & defense ETFs,
- drone mobility ETFs,
- disruptive automation funds,
- clean energy ETFs,
- IPO-focused ETFs.
Most importantly, one drone and urban air mobility ETF allocates more than 10% to BETA, signaling exceptionally strong thematic conviction.
This matters because institutional ETF ownership:
- improves liquidity,
- reduces collapse risk,
- and increases long-term visibility.
The market clearly still believes electric aviation remains a multi-decade growth opportunity.
Why the Stock Has Underperformed Despite Strong Technology
This is where things become complicated.
The technology story is strong.
The stock performance is not.
Why?
Because the market currently cares more about:
- certification timelines,
- commercialization speed,
- cash burn,
- and survival probability.
BETA still faces enormous execution challenges.
The company burns massive amounts of capital annually while generating limited revenue. Investors know additional funding rounds are likely.
The aviation sector is also brutally difficult:
- certification delays are common,
- manufacturing scale-up is expensive,
- infrastructure deployment takes years,
- and regulatory approvals move slowly.
Even excellent technology companies can struggle financially for extended periods.
This explains why the stock trades with very high volatility. The company’s beta of 3.18 reflects substantial market risk and speculative trading behavior.
What Needs to Happen for the Stock to Enter a Sustainable Bull Trend?
For BETA to transition from speculative IPO to long-term institutional winner, several milestones are critical:
1. FAA Certification Progress
This remains the biggest catalyst.
Without certification, revenue potential stays theoretical.
2. Commercial Aircraft Deliveries
The market needs proof that real commercial demand exists.
3. Scaling Infrastructure Deployment
Charging networks must expand meaningfully.
4. Strategic Partnerships
Defense, cargo logistics, and airline partnerships could dramatically improve investor confidence.
5. Improving Financial Visibility
Investors eventually need clearer paths toward:
- positive gross margins,
- scalable production,
- and reduced cash burn.
Bulls vs Bears: The Investment Debate
Bulls Say
Bulls argue that BETA is one of the most credible companies in the entire electric aviation sector.
They point to:
- real-world flight operations,
- integrated infrastructure strategy,
- strong technological execution,
- increasing ETF ownership,
- and practical commercialization pathways.
Supporters also argue the market is underestimating how valuable electric aviation infrastructure could become if the industry scales globally.
Some investors view the current weak stock performance as a rare opportunity to buy a future category leader before mainstream institutional adoption arrives.
Bears Say
Bears focus on financial reality.
The company is losing hundreds of millions annually while generating relatively little revenue.
They also argue:
- FAA timelines may take longer than expected,
- commercialization may remain slower than bulls anticipate,
- and dilution risk remains extremely high.
Competition is also intense. Major players like Joby and Archer possess stronger market visibility and large strategic backers.
Critics further point to the company’s extreme volatility and speculative nature.
Is the Stock Actually Undervalued?
This depends entirely on your time horizon.
Short-Term View
Short-term investors may continue struggling with:
- volatility,
- dilution fears,
- and uncertain profitability timelines.
The stock could remain highly speculative for years.
Long-Term View
Long-term investors may see something different:
- a functioning electric aviation ecosystem,
- infrastructure ownership,
- military applications,
- logistics deployment,
- and eventual market leadership potential.
If electric aviation truly becomes mainstream over the next 10–15 years, BETA could look remarkably cheap in hindsight.
But if adoption slows or certification timelines fail, the downside remains substantial.
Investment Evaluation
|
Factor |
Rating (1–10) |
Notes |
|
Growth Potential |
9/10 |
Massive long-term eVTOL opportunity |
|
Profitability |
2/10 |
Heavy losses and cash burn |
|
Valuation |
6/10 |
Potentially undervalued vs sector vision |
|
Market Position |
8/10 |
Strong operational execution |
|
Risk |
9/10 |
Certification and dilution risks |
|
Technical Picture |
4/10 |
Weak momentum despite strong fundamentals |
Overall Investment Score: 6.3/10
Final Verdict
BETA Technologies may currently be one of the market’s most misunderstood IPOs. Financially, the company still looks deeply speculative. But operationally, it may also be one of the few electric aviation companies genuinely building the infrastructure, ecosystem, and real-world deployment capabilities needed to survive long term.
The stock remains high risk, highly volatile, and dependent on execution. However, unlike many speculative IPOs, BETA at least appears to possess real technological substance behind the narrative.
One-Sentence Conclusion
BETA Technologies looks less like a failed IPO and more like a deeply speculative long-term infrastructure bet on the future of electric aviation — risky in the short term, but potentially massively undervalued if the industry scales as bulls expect.
Discover more from IPOSight
Subscribe to get the latest posts sent to your email.